- Practice Areas
- States
- About Us
- Resources
- Contact Us
- Divisions
- 844-941-2569
Michigan’s No-Fault system makes your selected PIP medical coverage level especially important, with options ranging from unlimited coverage to $50,000. Ged Lawyers handles your No-Fault claim and evaluates whether a third-party claim may provide compensation beyond your available benefits. Understanding which coverage tier applies to you is the first step in protecting your rights after a crash.
Years of Experience
Hospital Systems
Imaging Center
Orthopedic Center






A Michigan car accident can leave you dealing with injuries, medical expenses, and insurance questions. Under Michigan’s No-Fault system, your selected PIP medical coverage level can determine the benefits available for accident-related medical care, with coverage options ranging from unlimited to $50,000. Understanding your coverage early can help protect your claim.
Ged Lawyers builds claims around impact, medical treatment, vehicle damage, and losses caused by rear-end crashes.
When several drivers and insurers are involved, Ged Lawyers helps sort through fault, coverage, and conflicting accounts.
A Michigan car accident can involve both No-Fault benefits and a separate claim against another driver. Your injuries, the circumstances of the crash, and the evidence available can determine which legal options may apply. Your selected PIP coverage level is also important because Michigan allows different medical coverage options, including limits as low as $50,000.
Ged Lawyers reviews your accident, medical records, insurance policy, and available evidence to identify potential No-Fault benefits and determine whether you may have grounds for a third-party claim under Michigan law.
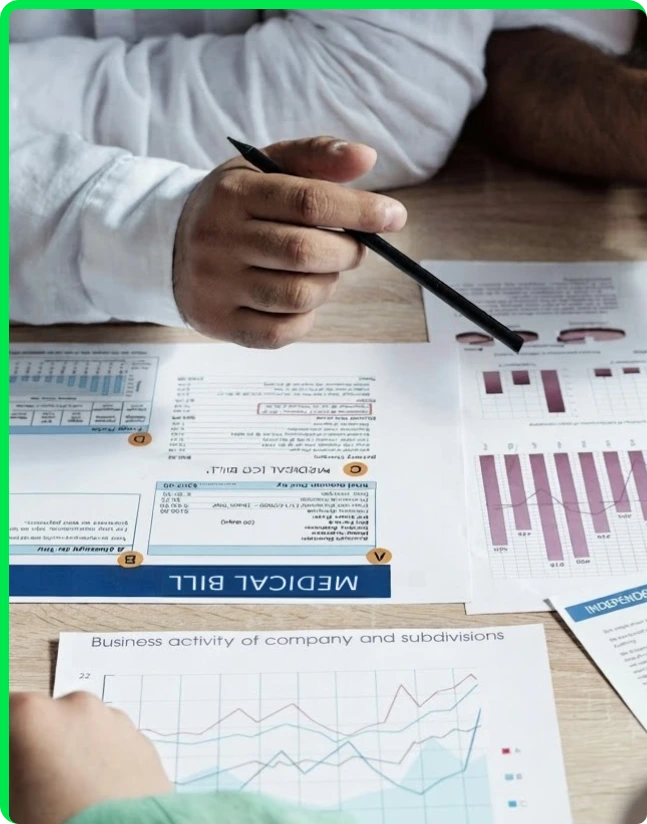
We collect reports, photos, witness details, and crash evidence.
We review medical bills, missed wages, repairs, and injuries.
We manage claim communication and respond to insurer disputes.
We prepare your case to pursue available compensation.
Ged Lawyers brings decades of legal experience to serious injury, insurance, property loss, and estate matters.
Our multilingual team helps clients communicate clearly, ask questions, and understand what is happening in their case.
Clients work with attorneys and support staff who prepare the case carefully and stay involved throughout the process.
Eligible injury clients pay no upfront attorney fees. Ged Lawyers is paid only when compensation is recovered.
Major verdicts and settlements show the firm’s experience handling serious,
high-value claims for injured clients.
Ged Lawyers has the manpower, experts, and legal resources to challenge insurers, corporations, and powerful defendants.
After a Michigan car accident, protect your health, document the crash, and review your No-Fault coverage. Your selected PIP medical coverage level can affect the benefits available for accident-related medical expenses.
Check for injuries and call 911 if emergency care is needed.
Photograph vehicles, damage, injuries, road conditions, and the crash scene.
Move away from traffic if you can do so without worsening your injuries.
Report the accident to police and obtain an official crash report.
Seek medical care promptly and keep your medical records and bills.
Collect names, contact information, insurance details, and vehicle information.
Check your policy to understand whether your PIP medical coverage is unlimited or subject to a selected limit.
Speak with a Michigan car accident lawyer about your No-Fault benefits and whether a third-party claim may apply.
Call 911 and report the crash. Michigan law requires reporting any accident involving injury, death, or apparent property damage of $1,000 or more under MCL 257.622, and the UD-10 crash report that follows becomes the foundational document for your PIP claim and any later lawsuit.
At the scene, photograph vehicle positions, damage, skid marks, and traffic controls before anything moves. On corridors like the Southfield Freeway, I-696, or the Lodge, wreckage is cleared fast and that evidence is gone within the hour.
Get evaluated the same day, even if you feel fine. Adrenaline masks soft tissue and head injuries, and treatment gaps give adjusters grounds to dispute causation later.
Notify your own insurer rather than the other driver's. Under Michigan No-Fault, your policy pays medical care and wage loss regardless of fault. File your written application for PIP benefits within one year of the crash. If you have no policy and none is available through a spouse or resident relative, apply to the Michigan Assigned Claims Plan within that same year.
Yes, but Michigan No-Fault limits when. Under MCL 500.3135, you can sue an at-fault driver for pain and suffering only if the crash caused death, permanent serious disfigurement, or serious impairment of an important body function. That last category is where most disputes live, and insurers argue it aggressively.
Serious impairment turns on whether the injury affects your general ability to lead your normal life. Courts examine what you did before compared to after: the job you can no longer perform, the sport you gave up, the lifting restriction your surgeon imposed. Objectively manifested injuries with imaging and surgical records carry more weight than subjective pain complaints.
Two other claims exist independently of that threshold. You can sue for excess economic damages when medical bills or wage loss exceed your chosen PIP level, under MCL 500.3135(3)(c). And Michigan's mini-tort allows recovery of up to $3,000 for vehicle damage your collision coverage does not pay.
You generally have three years from the crash date to file a third-party lawsuit.
Not always. A minor Southfield fender bender with no injuries, a clear police report, and a cooperative adjuster is a claim most people can close themselves.
Certain signals change that answer. If your insurer denies or cuts off PIP benefits, schedules you for an independent medical examination, or disputes whether your treatment is reasonably necessary, you are now in a contested claim with a company that handles thousands annually while you handle one.
Priority disputes are another trigger. When a passenger, pedestrian, motorcyclist, or resident relative is injured, Michigan's order of priority rules determine which insurer pays, and carriers routinely point at each other while bills go unpaid.
You should also get advice before recorded statements, before signing medical authorizations, and before accepting any settlement that closes your claim. Michigan's serious impairment threshold means the difference between a modest PIP recovery and a full third-party case, and that assessment is difficult to make while you are still treating.
Most Michigan car accident lawyers evaluate these questions at no cost.
The economics usually favor representation, and Michigan regulates the cost.
Under Michigan Court Rule 8.121, contingency fees in personal injury cases are capped at one third of the net recovery. In No-Fault benefit disputes, courts assess whether a fee is reasonable, and overdue PIP benefits carry 12 percent penalty interest under MCL 500.3142, along with the possibility of attorney fees paid by the insurer when a denial was unreasonable.
That structure matters. You pay nothing upfront, nothing hourly, and nothing if there is no recovery. The practical question becomes whether representation increases the outcome by more than the fee.
It frequently does in three situations: when the serious impairment threshold is contested, when medical bills approach or exceed your selected PIP tier, and when future care, attendant care, or reduced earning capacity must be valued rather than simply tallied.
For a straightforward property damage claim under the $3,000 mini-tort, hiring counsel rarely makes financial sense. For a disputed injury claim, it usually does.
It depends on how your auto policy is coordinated and which PIP tier you selected.
With uncoordinated coverage, your auto insurer pays first for accident injuries and your health plan is secondary. With coordinated coverage, which carries a lower premium, your health insurance pays first and PIP covers what remains. Michigan drivers often choose coordination without realizing it shifts deductibles, copays, and network restrictions onto them after a crash.
If you elected the $250,000 tier with PIP medical exclusions under the 2019 reform, your health plan becomes the primary payer entirely. That option is only available when you hold qualifying health coverage, defined as a plan that does not exclude or limit auto injury care and carries an annual individual deductible of $6,000 or less.
Practical gaps follow. Health plans commonly deny or restrict attendant care, home modifications, vehicle modifications, and replacement services that Michigan PIP is designed to pay. Health insurers also assert subrogation rights against any settlement you later recover from the at-fault driver.
Medicare's role depends on a choice you may have made at your last policy renewal.
Michigan's 2019 reform created a full PIP medical opt-out under MCL 500.3107d for drivers enrolled in both Medicare Parts A and B, provided every spouse and resident relative on the policy has qualifying coverage elsewhere. If you took that option, Medicare becomes your primary payer for auto injuries.
If you kept PIP at any level, your auto insurer pays first and Medicare is secondary until your tier is exhausted. Under the federal Medicare Secondary Payer rules, any conditional payments Medicare makes in the meantime must be reimbursed from a later settlement, and that lien is resolved before you receive funds.
The opt-out carries real exposure. Medicare does not cover attendant care, replacement services, home or vehicle modifications, or wage loss, all of which Michigan PIP covers. It also imposes deductibles and coinsurance that unlimited PIP does not. Serious brain and spinal injuries routinely generate costs Medicare will not reach.
Yes, though Michigan's reform created a specific interaction worth understanding.
Under MCL 500.3107c, drivers enrolled in Medicaid may select a $50,000 PIP medical limit, a tier unavailable to anyone else. It carries the largest premium reduction and the smallest cushion. Once that $50,000 is exhausted, Medicaid becomes the payer for continued accident-related care.
That transition changes what treatment looks like. Medicaid operates on its own fee schedule, prior authorization requirements, and provider network, and many specialists who accept No-Fault patients do not accept Medicaid. Care that was routinely approved under PIP can become difficult to obtain.
Michigan Medicaid also asserts a statutory right of recovery against any settlement or judgment connected to the injury. That lien is negotiated and satisfied before distribution, which reduces net recovery and should factor into how a case is valued.
If you have no auto policy at all, the Michigan Assigned Claims Plan caps PIP medical benefits at $250,000 rather than the amount you might otherwise have selected.
Michigan has no statute requiring replacement, but federal guidance and your PIP coverage both point toward it.
The National Highway Traffic Safety Administration advises replacing a child seat after any moderate or severe crash. A crash qualifies as minor, and the seat may be reused, only when all five conditions apply: the vehicle was driven from the scene, the door nearest the seat was undamaged, no occupant sustained injuries, airbags did not deploy, and the seat shows no visible damage.
Any one condition failing means replacement. Structural compromise in a car seat is frequently invisible, since stress fractures form in the shell and harness webbing stretches without any external sign.
Under MCL 500.3107, replacement can qualify as an allowable expense payable through your No-Fault benefits. Keep the damaged seat, photograph it, and document the manufacturer, model, and date of manufacture before disposal. Some insurers request the seat itself.
Michigan's child restraint law, MCL 257.710d, applies independently and continues to require an appropriate restraint regardless of the crash.
Mon-Sun: 8am– 5pm
Available by phone 24/7